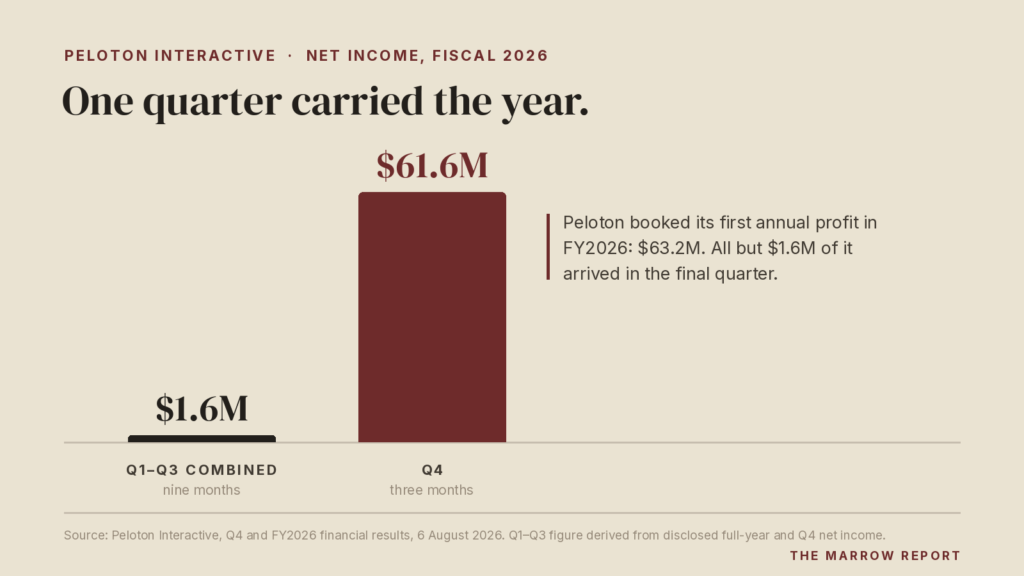
Peloton closed its 2026 financial year on 6 August with net income of 63.2 million dollars, the first annual profit in the company’s history. In the same year it ended with 2.553 million connected fitness subscribers, down 247,000, a decline of 8.8 percent.
Both of those things are true, and read together they describe the shape of the year. The profit did not arrive on the back of a larger subscriber base, because the subscriber base got smaller. It arrived in a business that costs materially less to run than it used to, and that is a different achievement with a different shelf life.
Where the profit came from, and when
The headline figures for the year are revenue of 2.446 billion dollars, adjusted earnings before interest, tax, depreciation and amortisation of 468.2 million, and free cash flow of 377.6 million. On any of those measures the turnaround is real and hard won.
Then look at the timing. Of the 63.2 million dollars of net income booked across the full year, 61.6 million landed in the fourth quarter alone. The first three quarters of a historic first profitable year produced roughly 1.6 million dollars between them. What the company achieved, precisely, is one decisively profitable quarter at the end of a year that was close to breakeven.
The forward guidance is where the year gets interesting. Peloton has guided to revenue of 2.3 to 2.4 billion dollars for its 2027 financial year, roughly four percent below what it just delivered. Over the same period it has guided adjusted EBITDA to 475 to 525 million dollars, above the 468.2 million it delivered this year, and free cash flow to at least 350 million. The company is forecasting a smaller business that earns more, and it is saying so plainly.
One detail deserves credit. Peloton counts a paused subscription as a churn event and excludes it from the subscriber base rather than parking it somewhere flattering. Fourth quarter churn was 2.2 percent on that basis. It is a conservative definition, and it makes the subscriber figure above more trustworthy than it would otherwise be.
Costs can be cut once. Subscribers have to be won every month.
Two ways to reach the same number
A profit earned by winning revenue and a profit earned by removing cost look identical on a profit and loss statement and behave differently afterwards. Cost reduction has a floor. There is a point at which the next cut takes something the customer can feel and the improvement stops. Revenue growth meets limits too, but they sit further out and they are set by the market rather than by the business itself.
Peloton’s own guidance is the most useful evidence of which lever it intends to pull next. Lower revenue alongside higher adjusted EBITDA describes a company planning to earn more from fewer customers rather than to reverse the decline in customers. That is a legitimate strategy, and the company is not disguising it.
The question the filing does not answer is where the subscriber line stops. The cost base that delivered 63.2 million dollars of net income was sized for a business with 2.553 million connected fitness subscribers. If the decline continues, margin has to keep absorbing it, and margin has less room each time.